All Categories
Featured


Tips for Managing Premiums With Pre-Existing Conditions
Table of Contents
The business you use to for life insurance coverage will ask about your family's medical history. Age Age16 2021 2425 3435 4445 5455 6465 +Protection Quantity Coverage AmountUnder$50,000 $50,000$100,000$100,000 $200,000$200,000 $300,000$400,000 $500,000$500,000 $1,000,000$1,000,000 $2,000,000$2,000,000 $5,000,000$5,000,000+ Protection Type Coverage TypeWhole LifeTerm LifeFinal ExpenseNot Sure Gender GenderMaleFemaleNon-Binary Shivani Gite is an individual finance and insurance writer with a degree in journalism and mass interaction.
A cancer diagnosis can bring a whirlwind of emotions and unpredictabilities. While your priority is most likely your health and treatment, it's natural to think about the futureincluding your liked ones' financial well-being. Life insurance coverage can provide monetary security and defense for your family. You may question: can you get life insurance coverage if you have cancer? While purchasing a life insurance coverage policy after a cancer medical diagnosis presents some difficulties, alternatives exist.
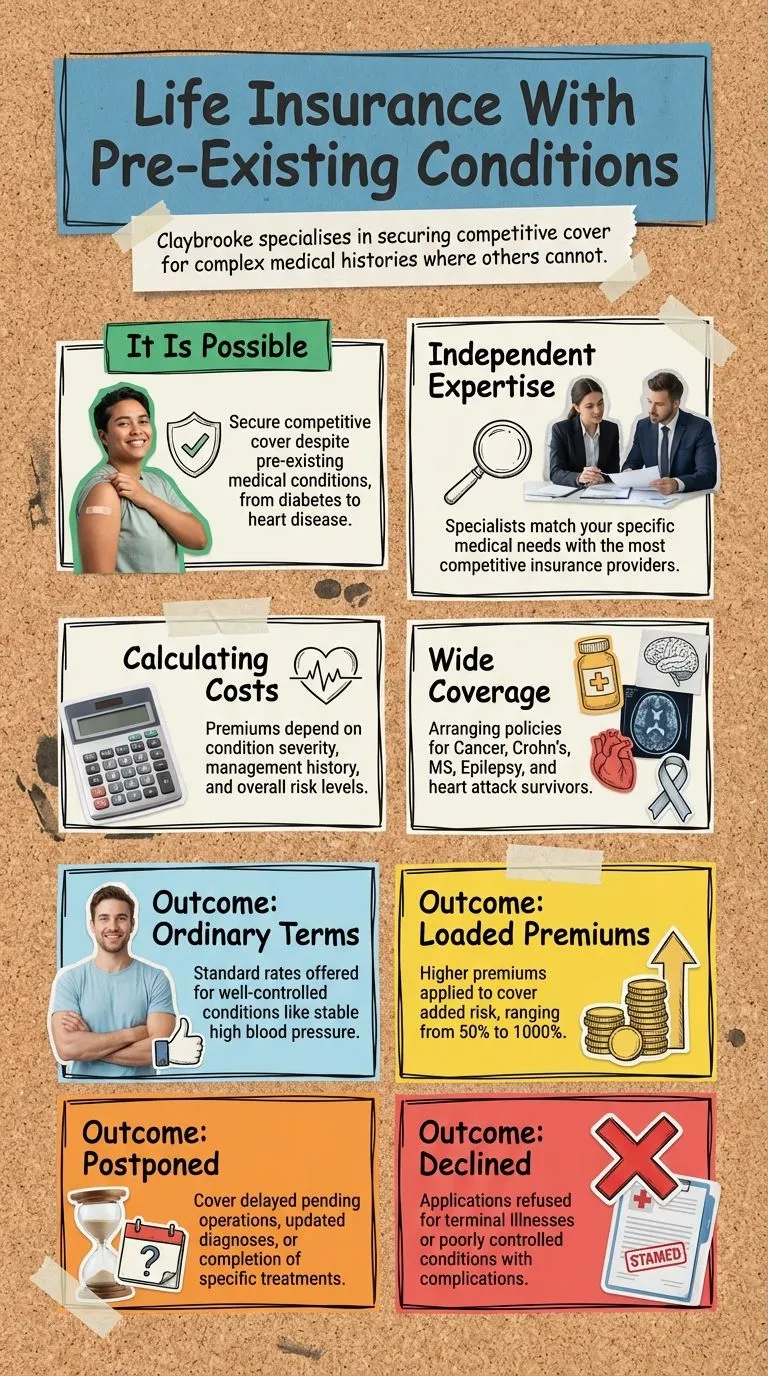
Some medical conditions, consisting of cancer, are thought about pre-existing. Life insurance companies completely assess each case, considering a couple of aspects.
Smart Tips for High Risk Travel Coverage
Whether you're going through treatment or in remission influences how insurers see the danger. Insurers typically see applications more positively if you have actually been in remission for a while. If you currently have life insurance coverage, a brand-new cancer diagnosis usually will not impact it. Guaranteed Acceptance Life Insurance So, can you get life insurance coverage if you have cancer? Yeshere are some coverage choices to consider.
Compared to other types of life insurance coverage, ensured approval policies may have lower protection quantities and higher monthly premiums. Simplified concern life insurance policies usually have a less extensive application procedure than standard protection types.
Lots of companies provide group life insurance as part of their advantages package. This term coverage can be available for cancer patients or survivors as it often has minimal health requirements, including no medical concerns or health exams. Nevertheless, group life insurance coverage normally uses lower protection amounts than specific policies you acquire yourself.
You might get approved for a traditional term or whole life insurance policy if you've been in remission for several years and have a favorable long-term prognosis. These policies may offer greater coverage quantities and possible benefits like cash value (in the case of whole life). However, the application process is usually more extensive and includes a medical examination.
Comparing Standard Versus Specialized Rates
Finding the best life insurance company after a cancer diagnosis is vital. Discover insurance companies or representatives who specialize in life insurance coverage for people with pre-existing conditions like cancer.
Don't think twice to get as much info as you need from the insurance company. Ask to describe policies, potential exemptions, and costs in advance. Navigating life insurance with a cancer diagnosis can feel overwhelming, you have choices. Research the offered policies, compare quotes, and work with the best insurance agent to find coverage that lines up with your needs.
Click here for more information. [skyword_tracking/] When a life insurance business rejects a claim and cancer is part of the validation, households are often left without the survivor benefit they were depending on and without a clear explanation of what takes place next. Insurers generally mention misrepresentation, product omission, or a policy exemption, and they send out a denial letter that can feel like the last word.
Wisconsin law gives insurance policy holders and beneficiaries the right to challenge a rejection. Insurance providers that handle claims in bad faith, suggesting they reject without a legitimate basis, hold-up unreasonably, or misrepresent policy terms, can face liability beyond just the original claim amount. Whether a rejection increases to that level depends upon the specific realities, including what was disclosed, what the medical records reveal, and how the insurer performed its evaluation.
We have actually also seen disputes including objected to medical records, contrasting physician declarations, and insurance companies who moved cash straight to a return-of-premium position without appropriate examination. At Wallace Law, we work with insurance policy holders and recipients who have actually been rejected, delayed, or deceived by insurance service providers after a cancer-related claim. We concentrate on first-party insurance coverage claims and bad faith insurance practices.
Funding a Special Needs Trust Through Life Insurance
A cancer medical diagnosis modifications everything including your financial priorities. One of the first concerns numerous patients and households ask is: The truthful response is: it depends, however you probably have more options than you think. This guide covers whatever you need to learn about and from what kinds of policies are still readily available, to for how long you might require to wait, to what it will cost, and what alternatives exist if conventional protection isn't an alternative today.
We'll cover those choices too. Quick response: Yes, but during active treatment, your alternatives are restricted to ensured problem policies, group employer protection, and last cost insurance coverage. Cancer survivors who are 210+ years in remission might qualify for conventional policies at higher-than-standard rates. If you are presently going through chemotherapy, radiation, surgical treatment, or other cancer treatments, the majority of traditional life insurance business will for term or whole life insurance.
However, "can I buy life insurance if I have cancer" and "can I get life insurance coverage if I have cancer" are not the same as "do I have zero alternatives." During active treatment, you can still access: no medical examination, no health concerns, approval guaranteed within eligible age varieties generally offered throughout open enrollment no matter health status developed for individuals with severe health conditions, usually $5,000$25,000 in coverage does not cover death from disease, however might be available and adds some monetary security In addition, if you currently have a life insurance policy, your diagnosis may enable you to trigger sped up survivor benefit, pursue a Living Benefit Loan, or check out a viatical settlement all covered in information listed below.
Once you've finished treatment and reached remission, the window for conventional life insurance coverage resumes but the timing and cost depend greatly on your specific history. Insurers evaluate cancer survivors on several factors: staging, grade, and histology matter substantially most insurance companies need 210 years of clean post-treatment history more youthful medical diagnosis can signal higher reoccurrence risk to underwriters surgical treatment alone vs.
With over 18 million cancer survivors in the United States, insurers have actually developed more nuanced underwriting designs that reflect the reality that numerous survivors live long, complete lives. Getting multiple quotes from several insurance companies is crucial, because underwriting standards vary considerably business to company. For specific resources for your cancer type, visit our cancer funds area or examine all monetary help options for cancer patients.

Latest Posts

How to Secure 2026 High Risk Life Insurance
Special Needs Planning: Essential Insurance Strategies for Every Family
New Standards for Impaired Risk Underwriting