All Categories
Featured

Policy Strategies for Disabled Trusts
Table of Contents

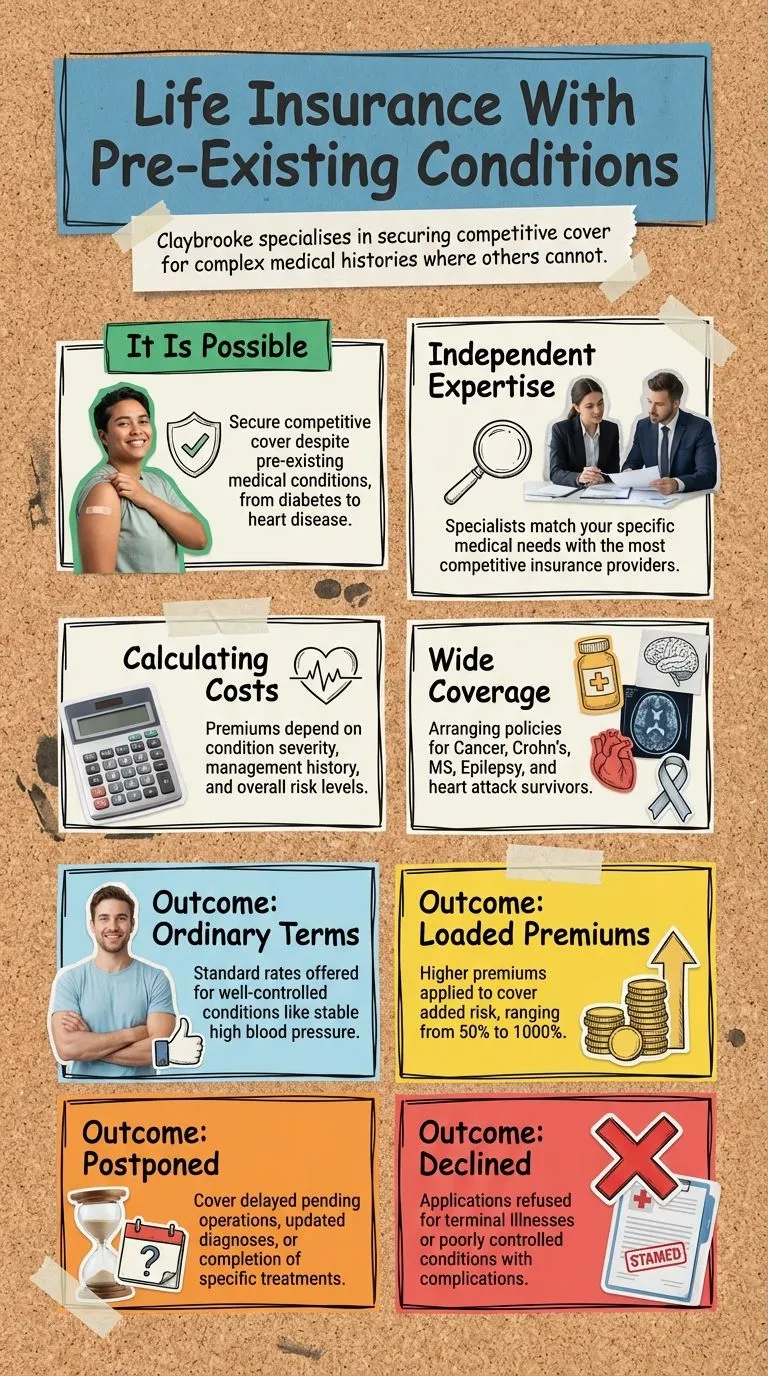
Life insurance can offer essential monetary protection for liked ones, however those with pre-existing conditions often have a more difficult time getting a life insurance coverage policy. Still, many medical conditions, consisting of diabetes, do not immediately disqualify a person for insurance coverage. People with diabetes can still get life insurance; they may have to pay more than a person without a pre-existing condition.
In this short article, we'll assist explain: Insurance service providers base premiums on the applicant's expected durability. Preexisting medical conditions can reduce life expectancy, which is why life insurance for some diabetics tends to be more expensive than it is for individuals without any preexisting conditions. Even when blood sugar level is well controlled, the illness can possibly trigger problems, so it is a threat element.
These consist of, but aren't restricted to: ObesityHeart diseaseHigh high blood pressure (high blood pressure)HypertensionStrokeIssues with eyes, teeth, and other organsKidney disease or failureNeuropathyLimb amputationHowever, not all diabetics are the very same. Life insurance coverage companies rate candidate danger based upon numerous aspects, consisting of case history, household case history, present health, age, and way of life (such as tobacco use).
Applicants with well-managed diabetes and no issues may get approved for more favorable policy terms. The life insurance coverage business will generally have you finish a medical underwriting procedure to identify your threat to insure. This can include a questionnaire that asks about your diabetes, in addition to the basic medical questions on the life insurance coverage application.
Insulin treatment, which is frequently needed for Type 1 diabetes and in some cases for Type 2 diabetes, may affect life insurance premiums. The insurer may also need medical records to validate your health history. In addition, you will frequently have to complete a physical examination (especially if you're obtaining a high coverage amount), and the life insurance company might also require a microalbumin test, which can assist detect early indications of kidney damage.
How Cancer Survivors Can Secure Life Coverage
complete underwriting policies" listed below.) As part of the underwriting procedure, the life insurance business will likewise ask about the kind of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. People with each kind of diabetes can still get life insurance, but depending on the base diagnosis, the application procedure may be more troublesome, and the protection offerings more minimal.
Veteran and Military InsuranceWhen it occurs later in life, that implies it has actually impacted your body and health for a much shorter length of time. Type 1 diabetes is typically identified in kids or teens, making it a greater threat, and for that reason, it is normally associated with higher premiums. Type 2 diabetes is typically identified at a later age than Type 1, so it has less time to impact the body.
If that holds true, and you have actually learned how to keep it under control with diet plan and exercise, you will likely get approved for the most budget friendly rates (in relation to others with diabetes). Even with Type 2 diabetes, individuals with diabetes-related complications and those who are insulin-dependent will find their life insurance coverage options more restricted and their premium expenses higher due to greater risk.
In the majority of circumstances, gestational diabetes goes away after delivering, but not constantly. In any case, pregnant females with gestational diabetes might wish to wait several months after giving birth before requesting life insurance coverage. Assuming the diabetes disappears, it will then be easier and cheaper to get a life insurance coverage policy.
Many term policies can convert to irreversible life insurance before the term expires without needing additional medical underwriting. If readily available, conversion can be an option to think about for individuals who purchased a term life insurance coverage policy before they were diagnosed with diabetes and desire to extend their protection. Irreversible policies, such as whole life insurance coverage or universal life insurance, are normally more costly, but they are designed to cover you for life.
Securing 2026 Life Insurance for Type 2 Applicants
2,3 It might be best to purchase as much life insurance as you'll require (and can pay for) as quickly as possible, rather than wait to include more later. This is due to the fact that life insurance coverage becomes more pricey the older you get, and a hidden condition like diabetes will normally raise the expense even more.

Latest Posts

How to Secure 2026 High Risk Life Insurance
Special Needs Planning: Essential Insurance Strategies for Every Family
New Standards for Impaired Risk Underwriting