All Categories
Featured


New Standards for Impaired Risk Insurance Underwriting
Table of Contents

Life insurance coverage can provide essential monetary security for loved ones, however those with pre-existing conditions typically have a more difficult time getting a life insurance coverage policy. Still, many medical conditions, consisting of diabetes, do not immediately disqualify a person for insurance protection. Individuals with diabetes can still get life insurance coverage; they may have to pay more than a person without a preexisting condition.
In this short article, we'll help describe: Insurance coverage companies base premiums on the candidate's expected longevity. Preexisting medical conditions can shorten life expectancy, which is why life insurance coverage for some diabetics tends to be costlier than it is for individuals without any pre-existing conditions. Even when blood sugar is well controlled, the disease can potentially trigger issues, so it is a risk factor.
These consist of, but aren't limited to: ObesityHeart diseaseHigh high blood pressure (hypertension)HypertensionStrokeIssues with eyes, teeth, and other organsKidney illness or failureNeuropathyLimb amputationHowever, not all diabetics are the exact same. Life insurance coverage companies rate candidate risk based on numerous elements, including medical history, family case history, existing health, age, and lifestyle (such as tobacco use).
Candidates with well-managed diabetes and no complications may receive more favorable policy terms. The life insurance business will usually have you complete a medical underwriting procedure to identify your danger to insure. This can include a questionnaire that asks about your diabetes, in addition to the standard medical questions on the life insurance coverage application.
Insurance for Chronic Kidney DiseaseInsulin therapy, which is typically needed for Type 1 diabetes and in some cases for Type 2 diabetes, may affect life insurance coverage premiums. The insurance business may likewise require medical records to validate your health history. In addition, you will often need to finish a physical examination (especially if you're making an application for a high coverage amount), and the life insurance coverage company might also require a microalbumin test, which can assist detect early signs of kidney damage.
Comparing Cancer Insurance Rates in 2026
full underwriting policies" below.) As part of the underwriting procedure, the life insurance coverage business will also ask about the type of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. Individuals with each form of diabetes can still get life insurance coverage, but depending on the base medical diagnosis, the application procedure may be more cumbersome, and the coverage offerings more restricted.
Insurance for Chronic Kidney DiseaseWhen it takes place later in life, that suggests it has actually impacted your body and health for a much shorter length of time. Type 1 diabetes is often diagnosed in kids or teens, making it a greater threat, and for that reason, it is normally associated with greater premiums. Type 2 diabetes is typically identified at a later age than Type 1, so it has less time to affect the body.
If that is the case, and you've found out how to keep it under control with diet and exercise, you will likely get approved for the most economical rates (in relation to others with diabetes). Even with Type 2 diabetes, individuals with diabetes-related problems and those who are insulin-dependent will discover their life insurance options more minimal and their premium costs greater due to higher risk.
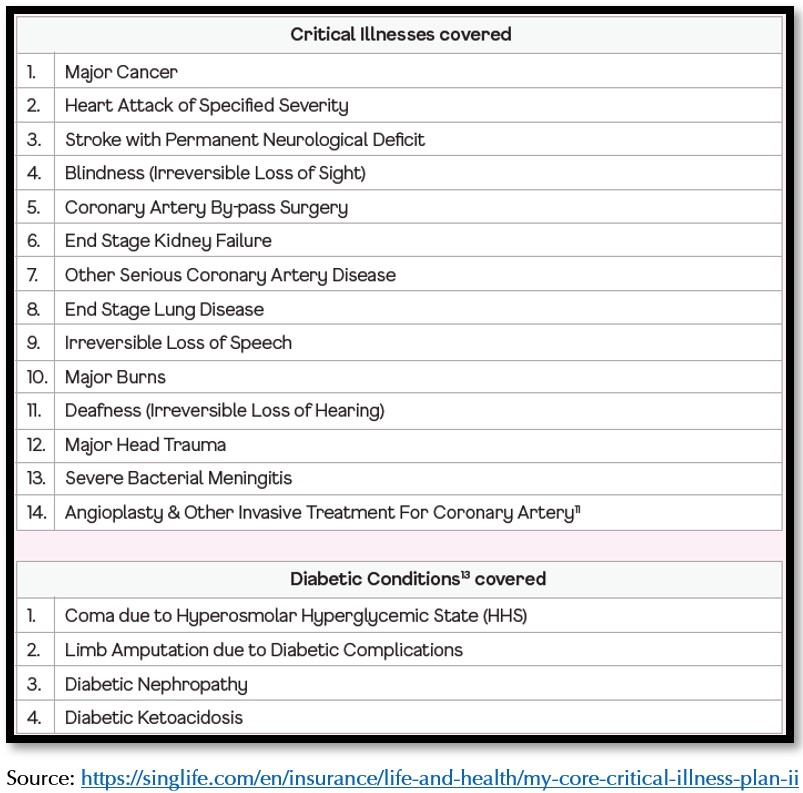
In most instances, gestational diabetes disappears after delivering, however not always. In any case, pregnant females with gestational diabetes might wish to wait several months after delivering before looking for life insurance. Assuming the diabetes disappears, it will then be simpler and less costly to get a life insurance coverage policy.
When requesting life insurance as a diabetic, there are 2 main points to think about: the kind of life insurance coverage policy and the type of insurance coverage underwriting. Term life insurance coverage policies will normally be the least costly choice in the sense that they provide the biggest survivor benefit per premium dollar. Numerous term policies can transform to long-term life insurance before the term ends without requiring extra medical underwriting. If offered, conversion can be an option to consider for people who bought a term life insurance policy before they were diagnosed with diabetes and desire to extend their protection. Irreversible policies, such as whole life insurance or universal life insurance, are normally more expensive, but they are developed to cover you for life.
Protection for HIV Status Individuals
2,3 It might be best to acquire as much life insurance as you'll require (and can pay for) as soon as possible, rather than wait to add more later. This is because life insurance becomes more pricey the older you get, and a hidden condition like diabetes will normally raise the cost further.

Latest Posts

How Diabetics Qualify for Modern Specialized Policies

2026 Policies for HIV Positive Applicants

Expert Underwriting for 2026 Impaired Risk