All Categories
Featured

High-Risk Travel Health Insurance for Pre-existing
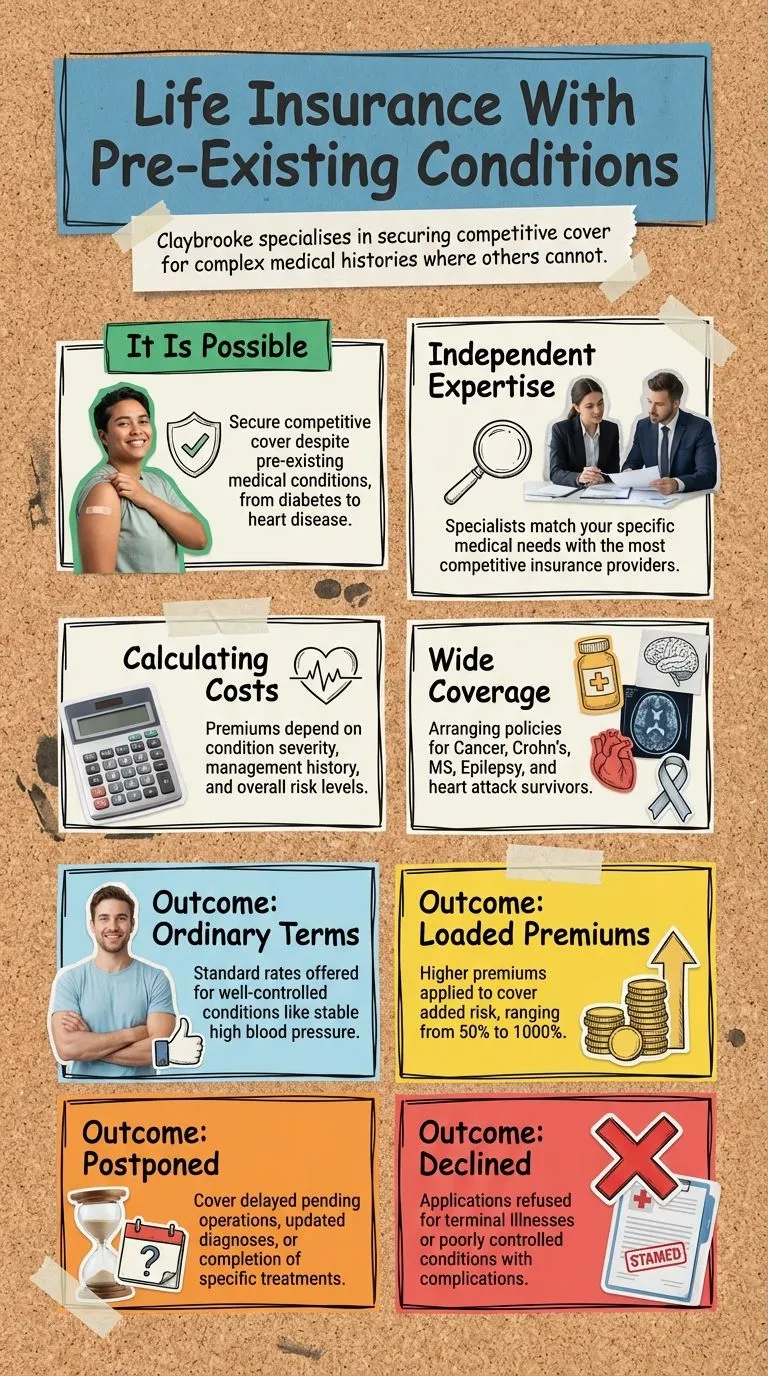
Injury insurance plan may particularly cover HIV, however normally only for physician and others at threat of getting the virus through their occupation. Totally underwritten3 applications at Zurich for an individual coping with HIV with an undetected viral load can look for all cover types. Depending on your health, we might use some covers, based on terms such as a greater premium, a shorter term policy, and/or exemptions. Insurers ask every consumer about their HIV status as part of the underwriting process for a life insurance coverage policy. At Zurich we ask every client if they have ever had a favorable HIV test or are awaiting the results of a test. There will be extra concerns asked if you reveal HIV favorable status, which will be about when the diagnosis was, treatment, any problems or AIDs associated diseases, and whether the HIV viral load is reduced or undetectable. If you inform us you're living with HIV and we are able to think about cover, we'll ask your dealing with doctor for a report. The report needs to consist of as much as date blood test results, CD4 lymphocyte counts, viral load tests and information of your treatment plan. If you do not have recent tests, we may ask you to get a blood test, either with a medical examiner of our option or through your treating physician. We'll inquire about your height, weight, alcohol or recreational drug use, current and past medical diagnoses and treatment, including mental health symptoms or medical diagnoses, history of sexually transmitted infections. Those sorts of concerns may appear invasive, however we're just attempting to get the information we need to properly assess any threats to your health, and these questions are asked to all consumers getting underwritten cover. If you are thinking about getting insurance coverage and are worried about any pre-existing conditions, it's a good idea to talk with a monetary consultant before you use. They can discuss your alternatives and support you through your application process. All insurance providers have different requirements. Not all insurance coverage companies ask the exact same questions or require the same level of information. While we hope you select Zurich, we motivate you to get at least three quotes from various insurers to make sure you get the finest cover at the very best cost for you. You might also ask your buddies and associates who they have insurance with and what their experience was like. These policies frequently have' automatic approval'but offer only a certain level of cover. You need to likewise examine the policy's Product Disclosure Declaration(PDS)for a Pre-existing Exclusion Provision (PEC ). A PEC suggests you are not covered for any condition you had before taking out insurance. This might not be best for you. Life insurance is a huge financial investment, and it deserves paying an expert to get excellent advice. Access to life insurance has enhanced in recent years: numerous insurers recognise that lots of HIV-positive.
people have a near normal life span. When using, you will be asked detailed concerns about your health. You will require to allow for the insurance provider to get more details from your doctors. This page reflects the personal finance market in the UK. Life insurance (also
Group Critical Illness Insuranceunderstood as'life assurance ','life defense','life cover'and 'death cover' )is typically created to pay a cash amount to your enjoyed ones when you pass away. Not everyone requires life insurance, however if your enjoyed ones depend on your income, if you have a home mortgage or if you have financial obligations, you might wish to consider it. Insurance providers are increasingly identifying that people coping with HIV are living to a normal life span, but your viral load, CD4 and other pre-existing conditions might affect the life insurance coverage cover you can get, including the premiums(month-to-month payments), length of policy and cash sum paid. It's not a great idea to withhold information about your HIV status or to lie when getting insurance. A range of organisations offer life insurance coverage(consisting of high street brokers, specialist brokers, life insurance business, banks and building societies). Each insurer has a procedure to assess whether you are eligible for life insurance with them; this procedure is called underwriting. Underwriting is used to examine the degree of threat (the possibility that you might pass away at a more youthful age ). During the application procedure an insurer will ask you a lot of individual questions

You might need to prepare yourself if you're not used to discussing your HIV status. You will likely be asked: When you were diagnosed What your CD4 count and viral load are What and just how much medication you are taking What other health conditions you have If you have actually had any symptoms, now or in the past. Numerous insurance providers will ask if you have ever used drugs in your life time, while some will inquire about drug use within the previous 5 or 10 years

Latest Posts

How to Secure 2026 High Risk Life Insurance
Special Needs Planning: Essential Insurance Strategies for Every Family
New Standards for Impaired Risk Underwriting